The rule in full
The SMSF borrowing change from 10 August 2026, in plain English, with the ATO pages it comes from. Checked against ATO guidance on .
What changed
A limited recourse borrowing arrangement (LRBA) is how an SMSF borrows to buy an asset. The lender’s rights are limited to that one asset, which is held in a separate trust until the loan is paid off.
From 10 August 2026, an LRBA entered into to buy real property can only buy business real property. It also has to be maintained or refinanced while the property still meets that definition, so the test applies for the whole life of the loan.
What didn’t change
LRBAs aren’t banned. An SMSF can still borrow to buy shares, other assets and business real property, and there are no changes to how LRBAs work or to the other exceptions to the borrowing ban.
Buying property without a loan isn’t affected by this change. The usual SMSF rules still apply to it.
Business real property
Business real property generally means land and buildings used wholly and exclusively in a business. The business can be yours or a tenant’s.
The test looks at the whole property. A use that is minor, insignificant or trifling may not stop a property qualifying, but a flat someone lives in is more than that. A shop with a flat on the same title generally won’t qualify.
Business real property is also one of the few assets an SMSF can buy from a related party at market value, and lease to a related party, such as your own business, at market rent.
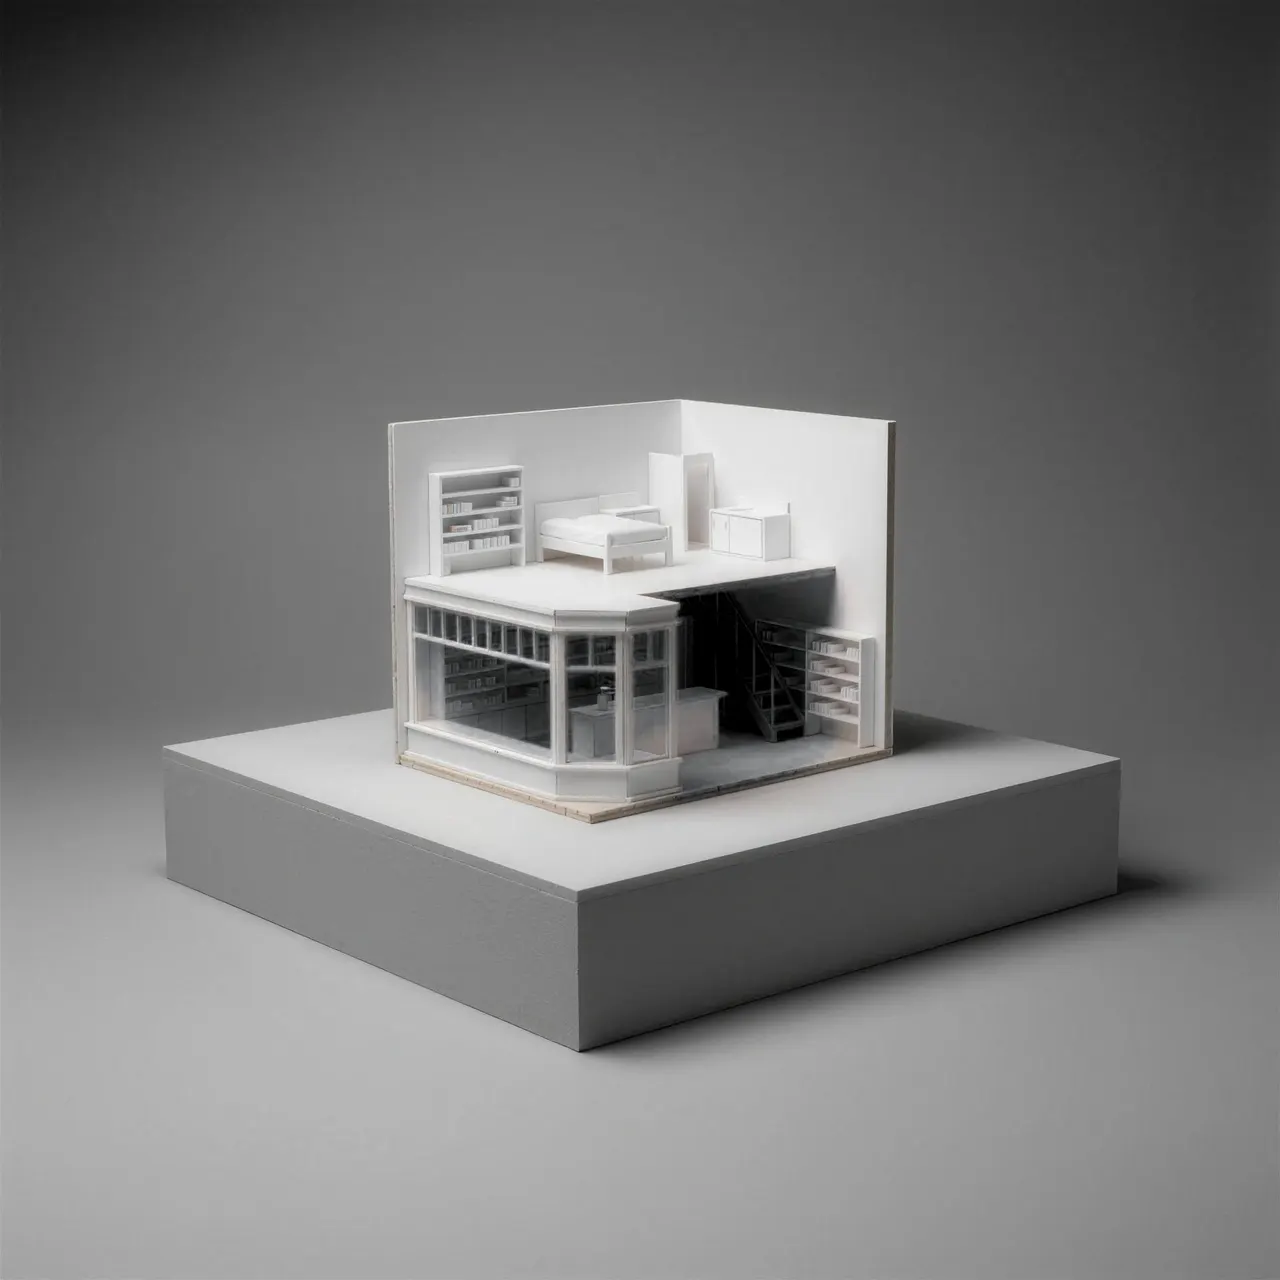
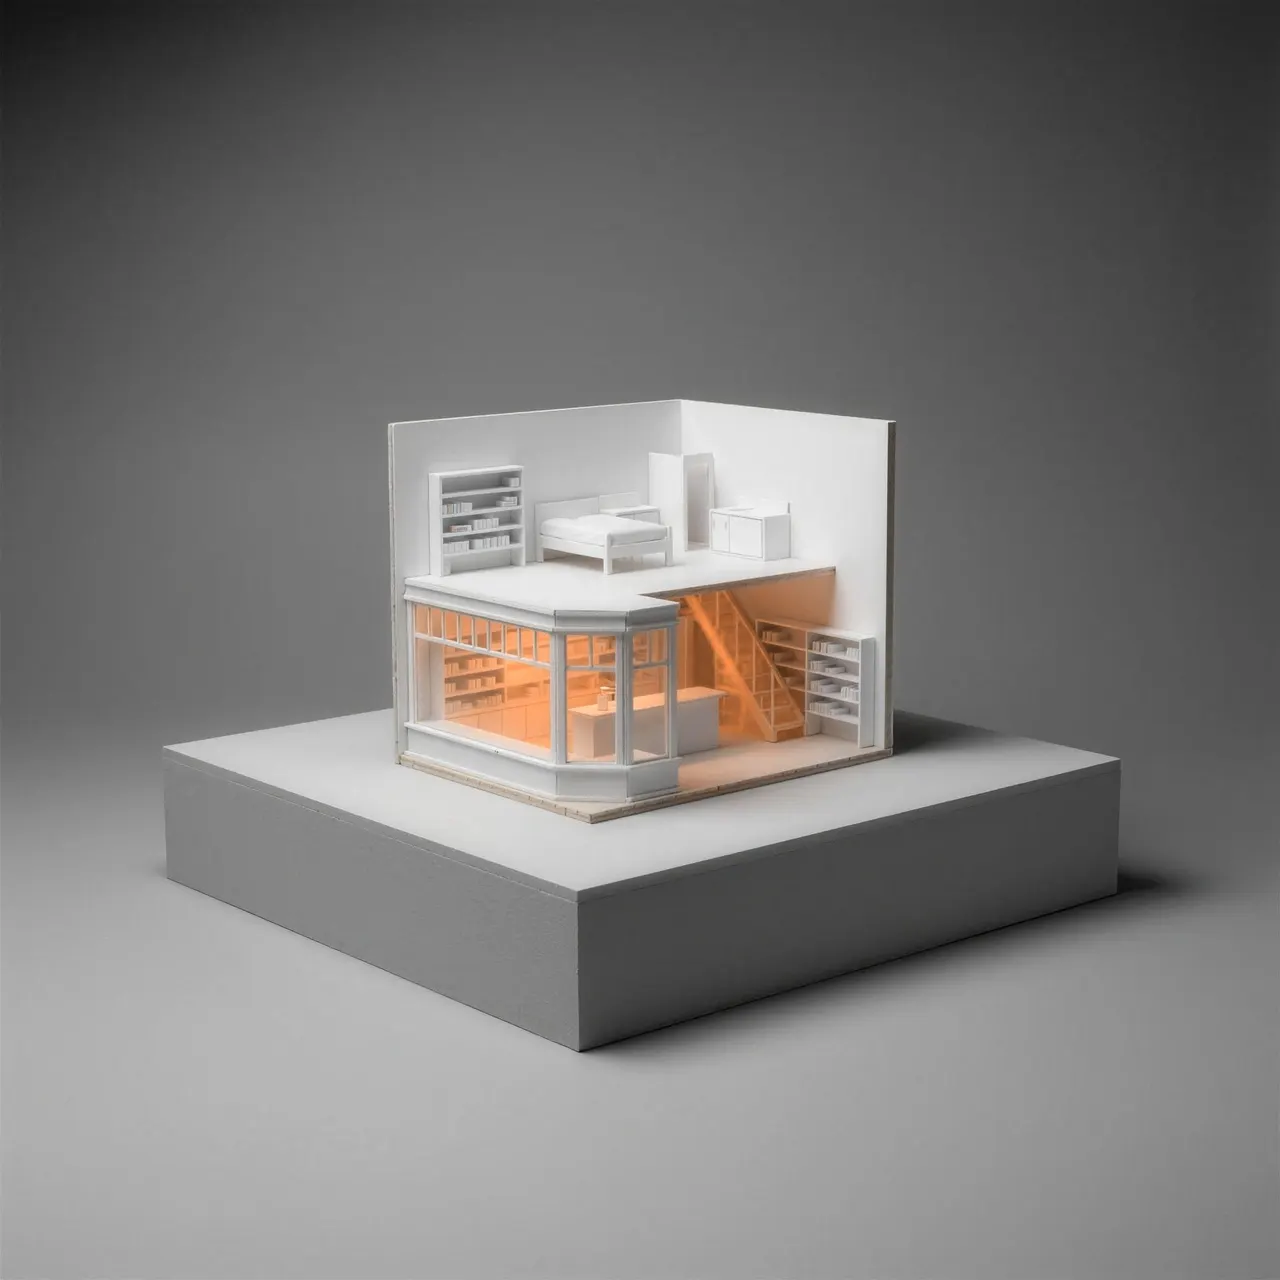
- Shop window
- Shop floor
- Back store
- Flat upstairs
Farms and the 2‑hectare rule
Property used in a primary production business can contain a dwelling used for private or domestic purposes and still count as business real property, if that dwelling sits on an area of no more than 2 hectares, and the main use of the whole property isn’t private or domestic.
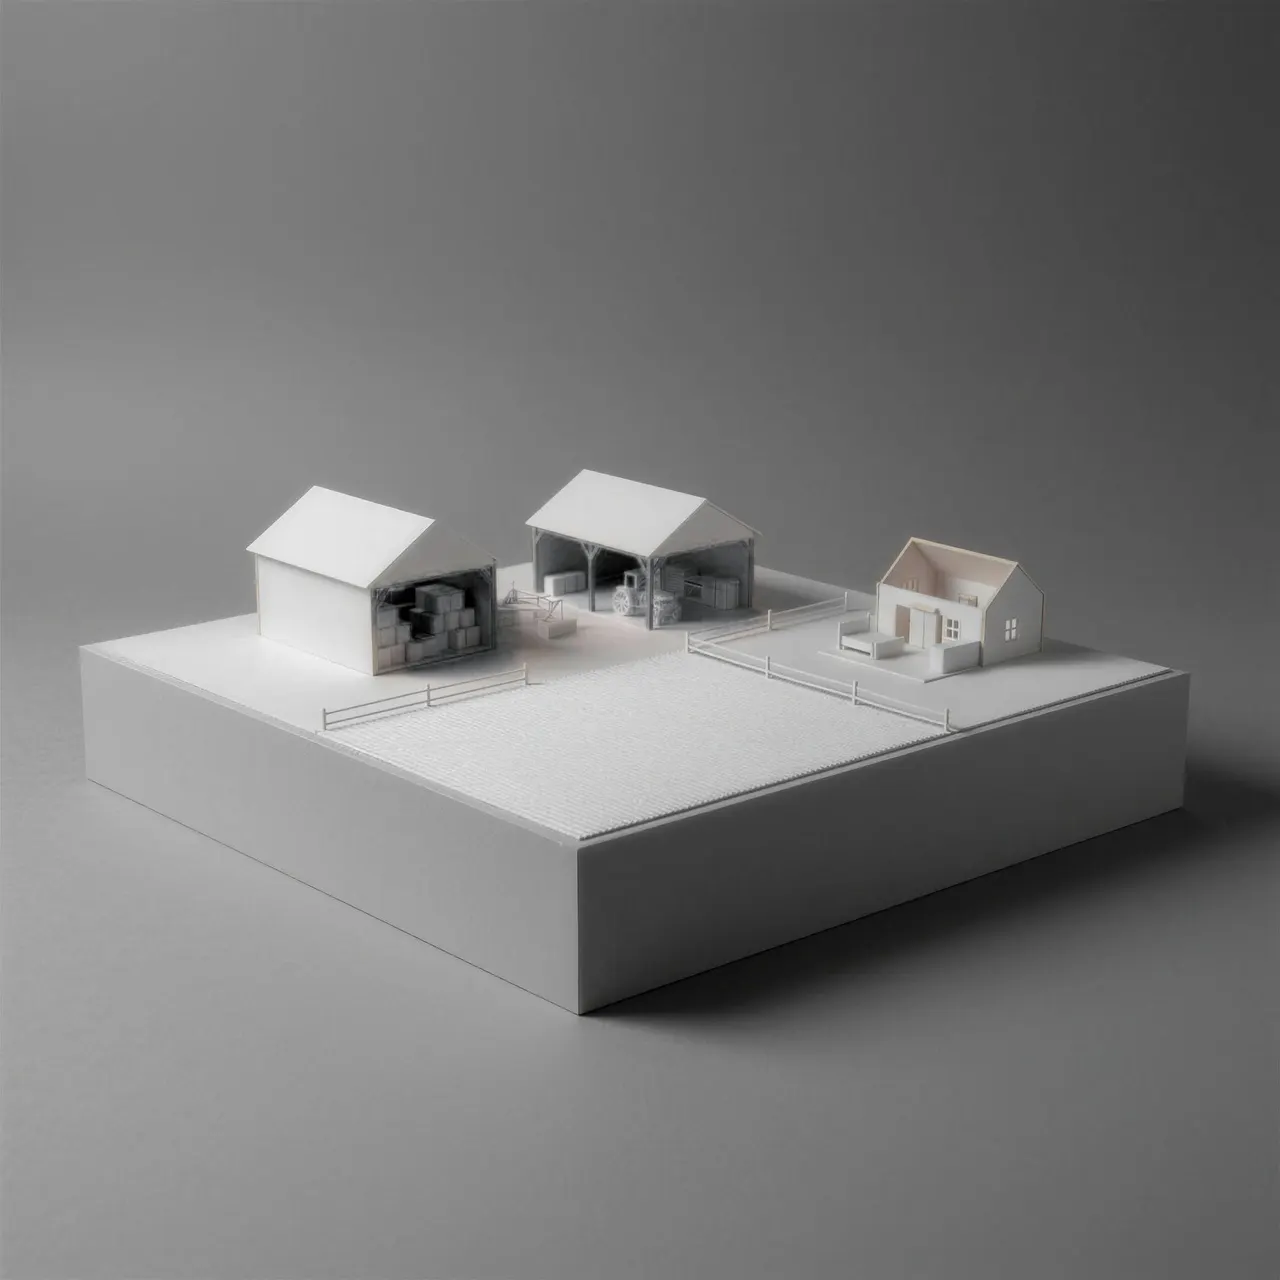
- Hay shed
- Machinery shed
- Homestead, 2 ha or less
Existing loans and refinancing
If the SMSF entered into an LRBA for real property before 10 August 2026, the change doesn’t apply to it. The fund can keep the loan, and can refinance it on or after the date. The property doesn’t need to be business real property.
The ATO treats refinancing as a new loan contract for the same asset, with the same lender or a new one.
Contracts exchanged before 10 August
If the SMSF exchanged a binding contract to buy real property before 10 August 2026, the change doesn’t apply, even if the loan is entered into or the contract settles on or after the date. That includes off-the-plan contracts.
Later variations generally don’t change this. A contract changed so much that its fundamental terms no longer exist may be treated as a new arrangement.
Every lender
The change applies to every LRBA, whoever the lender is: a bank, a non-bank lender or a related party. The identity of the lender doesn’t change whether the property must be business real property.
Questions people ask
Can an SMSF still buy residential property after 10 August 2026?
Yes, but not with a new loan. A limited recourse borrowing arrangement entered into from 10 August 2026 can only buy business real property. An SMSF can still buy a home with cash, on the usual rules: it can’t buy it from a related party, and members and their relatives can’t live in it or rent it.
Are SMSF loans banned?
No. Limited recourse borrowing arrangements aren’t banned. An SMSF can still borrow to buy an asset; the change is that a new loan for real property must be for business real property.
What happens to my existing SMSF property loan?
Nothing changes for a loan entered into before 10 August 2026. The fund can keep it and refinance it. The ATO treats refinancing as a new loan contract for the same property, with the same lender or a new one.
I exchanged contracts before 10 August 2026 but settle later. Which rules apply?
The old rules. If the SMSF exchanged a binding contract before 10 August 2026, the change doesn’t apply, even if the loan or settlement comes later. That includes off-the-plan contracts. Changing the contract’s fundamental terms later can start a new arrangement.
Does the change apply to loans from a related party?
Yes. It applies to every limited recourse borrowing arrangement, whoever the lender is: a bank, a non-bank lender or a related party.
What counts as business real property?
Generally, land and buildings used wholly and exclusively in one or more businesses, yours or a tenant’s. A minor, insignificant or trifling private use may not stop a property qualifying, but a flat someone lives in does.
Can my SMSF buy my business premises with a loan?
Yes, if the premises are business real property. An SMSF can buy business real property from a related party at market value and lease it to your business at market rent. Every part has to stay in business use for as long as the loan runs.
Can an SMSF loan buy a farm with a house on it?
Yes, if the property is used in a primary production business, the home and its private land take up 2 hectares or less, and living there isn’t the main use of the whole property.
What if a property stops being business real property during the loan?
The ATO says a new loan must be maintained or refinanced while the property still meets the definition of business real property. Talk to a licensed adviser before changing how any part of the property is used.
Words used here
- SMSF
- A self-managed super fund: a super fund run by its own members, who are its trustees or the directors of its trustee company.
- LRBA
- A limited recourse borrowing arrangement. The lender can only claim the asset bought with the loan.
- Business real property
- Land and buildings used wholly and exclusively in one or more businesses.
- Related party
- Broadly, a fund member, their relatives and the businesses and trusts they control.
- Exchange
- The point when both sides sign and swap a binding contract of sale. It usually comes weeks before settlement.
Sources
Read on 14 October 2026.